Florida Homeowners Insurance: What to Know Before You Make an Offer

Here's a scenario I never want my buyers to live through:
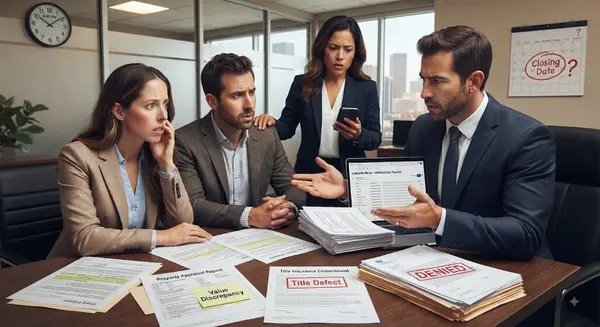
You find the perfect home. Your offer is accepted. You've told your family, picked paint colors and given notice on your lease. Then, a week before closing, the insurance quotes come back, and they're far higher than you expected. Or worse, the company won't insure the home at all until the roof is replaced.
In Florida, homeowners insurance can change a home's true monthly cost more than almost anything else. The good news: with a little homework before you make an offer, you can avoid nearly every insurance surprise.
What Florida insurers look at most
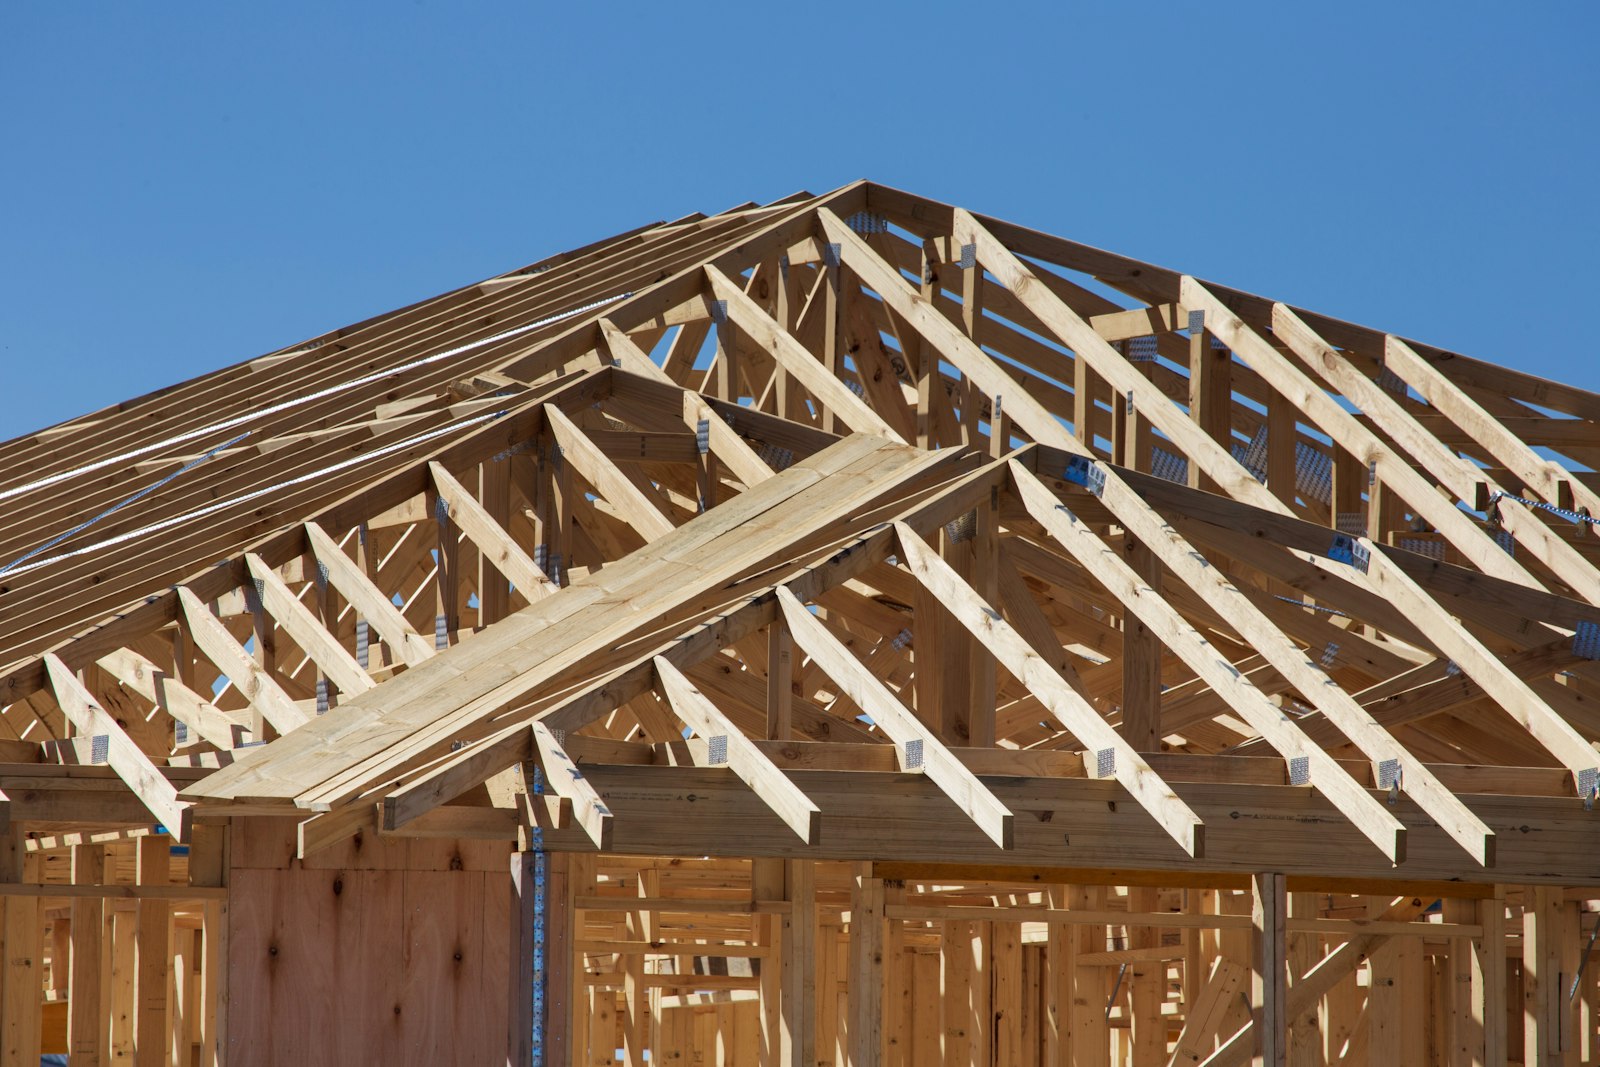
1. The roof This is the big one. Insurers want to know the roof's age, material and condition. An older roof can mean higher premiums, limited coverage, or a requirement to replace it before they'll write a policy.
Ask the seller: How old is the roof? Was it permitted? Any leaks or repairs?
2. The age of the home and its major systems For older homes, many insurers require a 4-point inspection covering the roof, electrical, plumbing and HVAC. Certain older electrical panels or plumbing materials can be a problem for some insurers.
3. Wind protection A wind mitigation inspection documents features that help a home resist hurricanes: roof-to-wall connections, roof deck attachment, impact windows or shutters, and roof shape. These features can earn meaningful premium discounts.
4. Flood zone This surprises many newcomers: standard homeowners policies don't cover flooding. If a home is in a high-risk flood zone and you have a mortgage, your lender will require separate flood insurance. Even outside high-risk zones, many Floridians choose to carry it.
5. Claims history Prior claims on the property can affect pricing. Ask whether the seller has made insurance claims and why.
Your step-by-step game plan
Before you make an offer:
- Ask the listing agent for the roof age and any existing 4-point and wind mitigation reports.
- Look up the address on FEMA's Flood Map Service Center to check the flood zone.
- Call your insurance agent with the address for a rough estimate, especially for older homes.
During your inspection period:
- Get real, written quotes from at least two or three companies. Prices vary widely.
- If needed, order a new 4-point or wind mitigation inspection along with your home inspection.
- If insurance is a deal-breaker, you still have options, like renegotiating or walking away, while you're within the inspection period.
Before closing:
- Bind your policy (and flood policy, if needed) and send proof to your lender.
Why new construction has an edge
Homes built to Florida's modern building codes typically have new roofs, stronger wind-resistant construction and newer systems. That often means better insurance pricing and easier approval. When I compare a new build against a resale home for a client, insurance is one of the first things we look at.
Common mistakes I see
- Waiting until after the inspection period to shop for insurance
- Assuming the seller's premium will be your premium (it often isn't)
- Skipping flood insurance because "it's not a flood zone"
- Not asking for the wind mitigation report, and leaving discounts on the table
Quick FAQ
How long is a wind mitigation report good for? Generally up to five years, as long as the home hasn't changed. Ask your insurance agent.
Is flood insurance available immediately? New flood policies often have a waiting period, commonly 30 days, unless they're tied to a loan closing. Don't wait until a storm is coming.
Can an older home still be a great buy? Absolutely. You just need to know the insurance cost up front and factor it into your offer.
The bottom line
Insurance isn't the fun part of buying a home, but it's one of the most important. Every cost breakdown I prepare includes an insurance estimate, so you know the true monthly cost before you commit, not the week before closing.
This is general information, not insurance advice. Get quotes and coverage details from a licensed insurance agent.
Lucas Gonzalez, REALTOR® | LPT Realty, LLC | (917) 295-1916 | thebulldogrealtorfl.com
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "
1400 International Pkwy, South Lake Mary, FL 32746, USA